Magnav Fintech Fifteen 2026
The Architects of Tomorrow’s Money
By Rizwan Zulfiqar Bhutta
Money has always reflected the ambitions of its time. From the earliest systems of trade and exchange to the establishment of modern banking, every major economic transformation has been accompanied by new ways of creating value, moving capital and connecting people. Today, that transformation is unfolding at extraordinary speed, shaped by technology, entrepreneurial imagination and a growing expectation that financial services should be more accessible, intelligent, transparent and responsive to the needs of a changing world. At the centre of this evolution stands financial technology, an industry that has moved far beyond the digitisation of payments to become one of the defining forces shaping the global economy.
Fintech has changed the relationship between individuals, businesses and money. It has challenged the traditional boundaries of banking, simplified international commerce, opened new routes into investment and credit, and enabled businesses to reach customers across borders with unprecedented efficiency. What was once the exclusive domain of large financial institutions is increasingly being reimagined through software, data, artificial intelligence and interconnected digital infrastructure. The significance of this change is not measured solely by transaction volumes or company valuations. It is also reflected in the opportunities created for entrepreneurs, the choices available to consumers and the possibility of bringing financial services to communities historically underserved by conventional institutions.
The scale of the transformation is evident in the industry’s economic performance. According to McKinsey’s April 2026 analysis, global fintech revenues reached approximately $650 billion in 2025, representing annual growth of around 21 per cent. Yet fintech still accounts for only a small proportion of the wider financial services industry’s revenues, suggesting that its evolution remains far from complete. The next phase will depend not simply on technological novelty, but on the ability to combine sustainable growth with reliable infrastructure, sound governance, meaningful customer relationships and long term commercial value. These developments point towards an industry entering a more mature and consequential chapter, in which the quality of innovation matters as much as its speed.
Artificial intelligence is emerging as one of the most influential forces in this new landscape. Financial institutions by Rizwan Zulfiqar Bhutta magazine 7 MAGNAV and technology companies are exploring its potential to improve fraud detection, strengthen risk assessment, automate administrative processes, personalise customer experiences and accelerate product development. Its application is also changing the way financial services are designed and delivered. As intelligent systems become increasingly capable of performing tasks on behalf of users, the industry must reconsider how transactions are authorised, how identities are verified and how accountability is maintained. The opportunity is substantial, but so is the responsibility.
Trust cannot be treated as an optional feature of financial innovation. It must remain fundamental to every system that handles people’s money, personal information and economic security.
Another important development is the growing interest in digital assets, tokenisation and new forms of payment infrastructure. These technologies could make certain financial transactions more efficient by bringing the transfer and settlement of assets closer together, potentially reducing unnecessary delays and operational complexity. The Bank for International Settlements has explored how tokenised central bank reserves, commercial bank money and government bonds could contribute to the next generation of the monetary system. Such developments illustrate the breadth of the transformation now under consideration, extending from everyday consumer payments to the underlying architecture of financial markets. Their long term value, however, will depend on appropriate safeguards, interoperability, legal certainty and responsible oversight.
Alongside technological progress, financial inclusion remains one of fintech’s most important purposes. A well designed financial product can make it easier for a small business to accept payments, for an individual to save towards a future ambition, or for an entrepreneur to access services that were previously difficult to obtain. The World Bank’s Global Findex Database 2025, based on surveys of approximately 148,000 adults across 141 economies, examines financial access and usage alongside mobile connectivity, internet use and digital safety. Its findings underline a fundamental principle: access to technology and access to meaningful financial services must advance together. Innovation is most valuable when it creates practical opportunities, particularly for women, lower income communities and people who remain excluded from established financial systems.
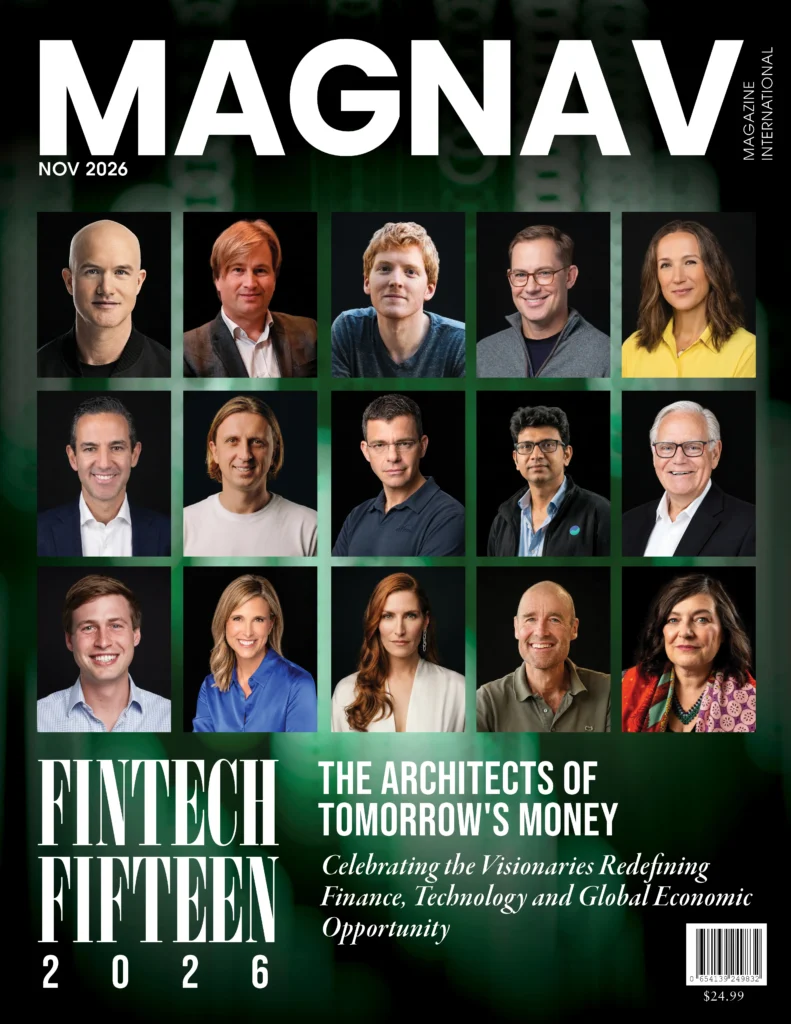
The leaders featured in Magnav Fintech Fifteen 2026 represent different dimensions of this remarkable evolution. Their work spans global payment networks, digital banking, consumer credit, financial data connectivity, investment platforms, enterprise processing, cryptocurrency infrastructure and the integration of financial capabilities into everyday software. Their approaches differ, reflecting the complexity of an industry that serves individuals, emerging businesses, multinational corporations and established financial institutions.
What connects them is their contribution to changing the way financial services are imagined, built and experienced. Patrick Collison’s work at Stripe illustrates the importance of infrastructure that enables businesses to participate in the digital economy. By making complex payment and financial operations accessible through software, Stripe has helped companies of different sizes operate across markets. Its 2025 annual update reported that businesses using its platform processed $1.9 trillion in total volume during the year, equivalent to approximately 1.6 per cent of global gross domestic product. The figure offers a striking indication of how deeply financial technology has become embedded in contemporary commerce.
Nik Storonsky has helped reshape expectations of everyday banking through Revolut, while Anne Boden’s work in establishing Starling Bank demonstrated the potential of a digital native institution built around modern banking technology. David Vélez and Lalit Keshre have pursued another essential ambition: expanding access to financial products and investment opportunities in markets where conventional services have often presented considerable barriers. Their work illustrates how mobile technology, simplified onboarding and customer centred product design can bring financial participation closer to a wider population.
Elsewhere, Zach Perret’s Plaid has helped connect financial accounts with the digital applications that depend on them, while Pieter van der Does has built Adyen around an integrated approach to enterprise payments. Kristo Käärmann’s Wise has challenged established expectations around international money transfers, and Stephanie Ferris leads FIS in the complex business of modernising financial technology systems that support banks, merchants and capital markets. Each represents a different part of the infrastructure that allows money to move through an increasingly connected world.
The transformation also extends into consumer finance and investment. Max Levchin has helped develop alternative approaches to point of sale credit through Affirm, while Sarah Levy leads Betterment in digital wealth management. Chris Britt’s work at Chime has brought attention to consumer banking models designed around reduced fees and everyday financial needs. Angela Strange has championed the integration of financial services into businesses beyond traditional banking, recognising that payments, lending and insurance can become natural extensions of digital platforms. Brian Armstrong’s work at Coinbase has contributed to the development of regulated digital asset services, while Jim Marous and Spiros Margaris have influenced industry thinking through research, strategic insight and investment perspectives.
These contributions do not suggest that every fintech model is without challenges, nor that every innovation will a chieve its intended promise. Financial technology operates within a demanding environment shaped by regulation, competition, cybersecurity threats, consumer expectations and changing economic conditions. Growth must be supported by resilience. Convenience must be balanced with privacy. New financial products must be assessed not only for their commercial potential, but also for their transparency, suitability and wider implications. The leaders who shape the industry’s next chapter will be those who understand that lasting progress requires both ambition and discipline.
This is also why recognition matters. Industries advance through the efforts of individuals who are prepared to question established assumptions, invest in difficult ideas and build systems whose significance may extend well beyond their original purpose. Their achievements deserve to be examined in context, their ideas considered critically and their contributions recognised as part of a wider story about economic and social change.
For Magnav, the return of Fintech Fifteen in 2026 marks the second year of a dedicated editorial initiative celebrating the people helping to shape this evolving financial landscape. The continuation of the project reflects our belief that fintech deserves sustained attention, not simply as a technology sector, but as a force influencing commerce, entrepreneurship, investment and everyday life. Our purpose is to bring together a diverse selection of contributors whose work illuminates the many directions in which financial innovation is moving, while acknowledging the ideas, decisions and leadership that have helped bring the industry to its present position.
The second edition also offers an opportunity to look beyond individual achievements and recognise the interconnected nature of progress. No payment platform exists in isolation. Digital banks depend on secure infrastructure, investment applications depend on trusted data, and emerging financial products depend on the institutions, regulations and technologies that support them. The future of fintech will be shaped through this combination of specialised expertise, collaborative development and the ability to respond to needs that continue to change.
The fifteen names presented in this edition therefore represent more than a collection of prominent individuals. Together, they offer a perspective on an industry that is continually redefining its boundaries. Their stories reveal how technology can remove friction, how thoughtful design can widen participation and how infrastructure can create opportunities for businesses operating on a global scale. They also remind us that financial progress is ultimately measured by the value it creates for people, organisations and economies.
As Magnav presents its Fintech Fifteen for 2026, we celebrate the vision to imagine better systems, the determination to bring them into existence and the responsibility required to sustain them. The future of money will not be shaped by technology alone. It will emerge from the judgement of those who build it, the trust of those who use it and the principles that guide its development. These are the architects of tomorrow’s money, and their work is helping define the financial possibilities of the years ahead.